
How to Ask for a Raise When You're Underpaid: A Guide for Women in Midlife
Here is something I see constantly in my work with women.
She has been in her role for years. She is good at it. She has taken on more responsibility than her job description ever anticipated. And she has not asked for a raise in a very long time, maybe ever, because it feels awkward or presumptuous or like she should just be grateful for what she has.
And the longer she waits, the more it costs her. Not just today. Every year she is underpaid compounds. It affects her bonuses, her retirement contributions, her Social Security calculation, and every raise that builds on that base going forward.
Asking for a raise is not aggressive. It is not arrogant. It is one of the most financially consequential things you can do, especially in midlife when you are in the prime earning years that matter most for building wealth and funding the retirement you actually want.
Here is how to do it.
Start With Clarity: Know What You Are Worth and What You Want
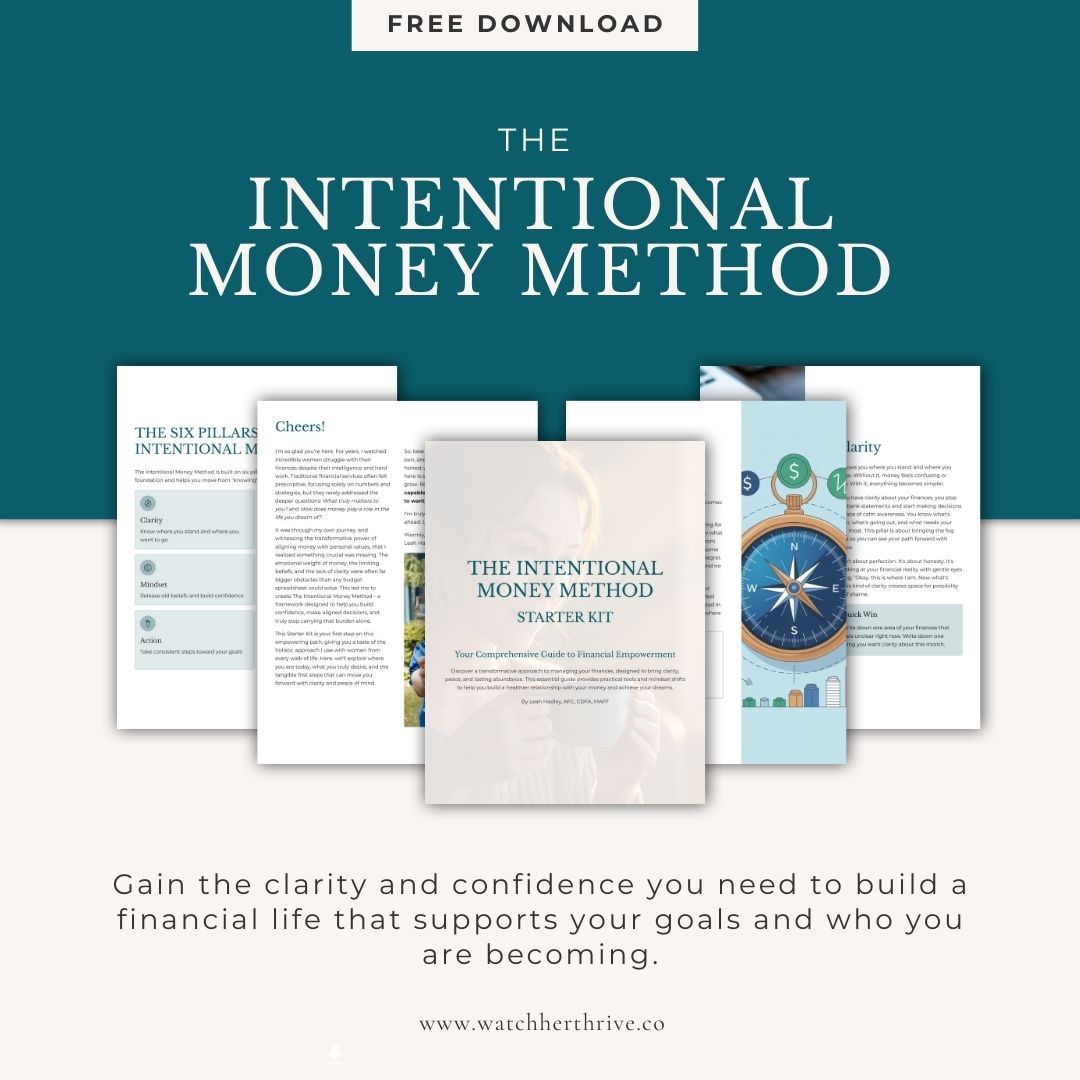
The first pillar of the Intentional Mo...
How to Make Extra Money Fast: Practical Strategies for Women in Financial Transition
There are moments in life when you need money and you need it now.
Maybe you are in the middle of a divorce and the finances are complicated. Maybe you are between jobs and the gap is longer than you planned. Maybe an unexpected expense wiped out your buffer and you are trying to rebuild faster than your regular income allows.
Whatever brought you here, I want to say two things. First, this situation does not reflect your worth or your capability. Financial pressure is something almost every woman I work with has navigated at some point. You are not behind. You are in a moment. Second, there are real, practical things you can do right now to create some breathing room.
These strategies are not a long-term financial plan. They are a bridge. A way to generate cash in the short term while you build the foundation that actually lasts. That longer-term work matters. But first, let's talk about right now.
Start With What You Already Have
The fastest way to genera
...How to Negotiate a Higher Starting Salary (and Why Most Women Leave Money on the Table)
Let me tell you something I've seen play out more times than I can count in my nearly two decades as a financial planner: women consistently underestimate their value at the negotiating table, and it costs them for years.
When you accept a salary that's lower than what you're worth, you're not just leaving money on the table today. You're compressing every raise, every bonus, and every retirement contribution that builds on that base for the rest of your career. The financial ripple effect of underselling yourself is real, and it's one of the most important money conversations I have with my clients.
Here's the truth: salary negotiation is not aggressive. It's not awkward. It's not arrogant. It's intentional.
And that's exactly how I want you to approach it.
Whether you're returning to the workforce after stepping away to raise your kids, making a career pivot, or simply ready to stop being underpaid, this is your moment. You have skills, experience, and val
...How to Be a Positive Money Role Model for Your Kids at Any Age

Your kids are watching you with money. They always have been.
Not in the formal, sit-down-and-teach-a-lesson kind of way. In the ambient, everyday kind of way. They watch how you react when an unexpected bill arrives. They notice the tension in your voice when money comes up. They absorb your beliefs about what is possible, what is safe, what people like us do with money.
Long before they ever open a bank account, your kids are building their money beliefs from what they see in you.
That is both a responsibility and an opportunity. And it does not expire when they turn 18.
If you are in midlife, you are likely parenting across a wide range of ages right now. Maybe you have teenagers at home and a college student simultaneously. Maybe your kids are already launched and you are wondering what money messages stuck and which ones you wish you had done differently. Maybe you are rebuilding your own financial foundation and you want to do it in a way that models something better than wha...
Leah Hadley, AFC, CDFA, MAFF
Leah Hadley, AFC® CDFA® MAFF™, is a bestselling author and financial planner with over 20 years of experience helping women build wealth with intention. She is the founder of Watch Her Thrive and Intentional Wealth Partners, and the author of Intentional Money: The Modern Woman's Guide to Building Wealth, Purpose & Peace.

Amazon Affiliate Disclosure
Watch Her Thrive is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to amazon.com.
Investment Advisory Disclosure:
Leah Hadley is a Licensed Investment Adviser Representative and the Founder of Intentional Wealth Partners, a Registered Investment Adviser. Advisory services are offered exclusively through Intentional Wealth Partners.
Watch Her Thrive is not a Registered Investment Adviser and does not provide individualized investment advice, financial planning, or securities recommendations. All content provided through Watch Her Thrive is for educational and informational purposes only.