
Understanding Your Credit Rating: A Plain-English Guide to Your Credit Score
Let me ask you something. When was the last time you actually looked at your credit score? Not the number your banking app flashes at you, but the thing underneath it.
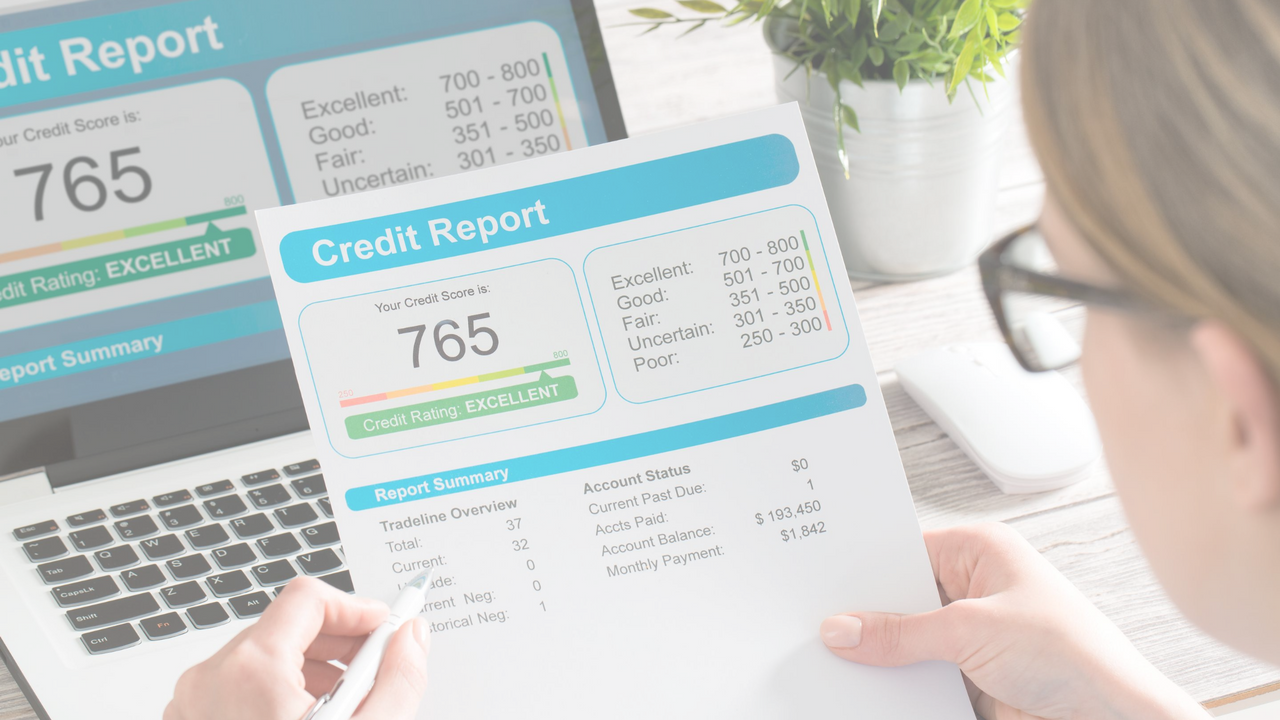
Your credit rating is a three digit number between 300 and 850 that predicts one thing: how likely you are to repay what you borrow. That number decides whether you get approved for a mortgage, what rate you pay on a car loan, and in many states what you pay for insurance. Understanding your credit rating is not about obsessing over the number. It is about knowing which five things move it, so you stop guessing.
Here is what I see over and over. Smart, capable women who can run a household budget in their head have never been told how the score is actually calculated. That is not a gap to feel bad about. Nobody teaches this.
What the number actually measures
The range runs from 300 to 850, and higher means lower risk to a lender.
You do not have one credit score. You have several. Different scoring models and different credit bureaus produce different numbers, which is why the score in your credit card app may not match the one your mortgage lender pulls. That is normal. The behaviors that move one score move them all.
The five things that move your credit score
FICO, the most widely used model, groups everything into five categories. These are the actual weightings.
Payment history: 35%
Paying on time is the single biggest factor in your credit score, by a wide margin.
It is also the least interesting one, which is probably why it gets skipped in conversation. If you are missing payments, you do not have a credit problem. You have a system problem, and that is fixable this week. Automating your bill payments removes the decision entirely.
Amounts owed: 30%
This is your credit utilization, the ratio between what you owe and the total credit available to you. A common target is keeping it under 30%, and lower is better.
Maxing out a card can hurt even if you pay it off in full, because the balance reported to the bureaus is usually the statement balance, not the balance after you pay. If you want a quick improvement, paying a card down before the statement closes does more than paying it after. It also helps to understand which debts are working for you and which are not.
Length of credit history: 15%
Older accounts help you, which is the argument for not closing the credit card you have had since college.
Closing an old account can shorten your average account age and cut your available credit at the same time, so it hits two factors at once. If the card has no annual fee, leaving it open and using it occasionally usually serves you better than tidying it away.
New credit: 10%
Every application for new credit creates a hard inquiry, and several in a short window signals risk to a lender.
Checking your own score is a soft inquiry and changes nothing. And when you shop for a mortgage or an auto loan inside a short window, multiple inquiries are typically treated as one, so rate shopping does not penalize you the way people fear.
Credit mix: 10%
Lenders like to see that you can handle more than one kind of credit, such as a card alongside an installment loan.
This is the smallest factor and the one least worth engineering. Do not open a loan you do not need in order to improve a mix that accounts for a tenth of the score.
The part nobody says out loud
Most women who avoid their credit score are not avoiding the number. They are avoiding what they think the number says about them.
It does not say anything about your character. It is a repayment prediction built from five inputs, and every one of them responds to changed behavior. A score is a snapshot, not a verdict. Avoidance costs more than the number ever will.
The one thing to do this week
Pull your credit report and read it. Not the score, the report.
You are entitled to free reports from all three bureaus at AnnualCreditReport.com. Read yours for errors, accounts you do not recognize, and anything marked late that you know you paid. Errors are more common than people expect, and disputing one is often the fastest way to move a score.
That is one hour, once. Then set a reminder to do it again in six months.
Frequently asked questions
What is a good credit score?
Scores run from 300 to 850. Generally, above 740 is treated as very good and above 800 as excellent, though the exact cutoffs vary by lender and by scoring model. For most borrowing, the meaningful thresholds sit around 620, 680, and 740, because those are where better rates tend to start.
Is a credit rating the same as a credit score?
In everyday use, yes. People say credit rating and credit score interchangeably to mean the three digit number that predicts how likely you are to repay. Credit ratings also describe grades assigned to companies and governments, but when the term applies to an individual, the two mean the same thing.
Does checking my own credit score lower it?
No. Checking your own score is a soft inquiry and has no effect at all. Only hard inquiries, which happen when a lender reviews your credit because you applied for something, can affect your score, and each one has a small impact that fades over time.
How long does it take to improve a credit score?
It depends on what is holding it down. Paying off a high balance can show up within one or two billing cycles. A late payment loses influence over months and drops off after seven years. Rebuilding after something serious takes longer, but the direction changes as soon as the behavior does.
Why do I have more than one credit score?
Because there is more than one scoring model and more than one credit bureau. FICO and VantageScore calculate differently, and Equifax, Experian, and TransUnion do not always hold identical information. Small differences between your scores are normal.
Where this goes next
Understanding your credit rating is a Clarity move. It is looking at where you actually are, without judgment, and Clarity is the pillar everything else in the Intentional Money Method rests on.
The harder part is what comes after. Knowing what to do and doing it consistently are two different problems, and the second one is not solved by more information.
That is what the Empowered Sisterhood is for. It is the Support pillar, the room where women work on this alongside each other instead of alone. If you read this far and recognized yourself somewhere in it, come see what it is.
Free: Intentional Investing for Women
My 24 page guide to aligning your portfolio with your goals. If investing has always felt like a language other people speak, start here.
Leah Hadley, AFC, CDFA, MAFF
Leah Hadley, AFC® CDFA® MAFF™, is a bestselling author and financial planner with over 20 years of experience helping women build wealth with intention. She is the founder of Watch Her Thrive and Intentional Wealth Partners, and the author of Intentional Money: The Modern Woman's Guide to Building Wealth, Purpose & Peace.

Amazon Affiliate Disclosure
Watch Her Thrive is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to amazon.com.
Investment Advisory Disclosure:
Leah Hadley is a Licensed Investment Adviser Representative and the Founder of Intentional Wealth Partners, a Registered Investment Adviser. Advisory services are offered exclusively through Intentional Wealth Partners.
Watch Her Thrive is not a Registered Investment Adviser and does not provide individualized investment advice, financial planning, or securities recommendations. All content provided through Watch Her Thrive is for educational and informational purposes only.